⭐ 5-Star Google Reviews 🏦 170+ Lenders 📊 30+ Years’ Experience

LET TO BUY MORTGAGES SPECIALISTS


Keep Your Existing Home, Release Equity And Buy Your Next Property


Specialist Lenders | Release Equity | Structured Dual Approvals | Move Without Selling

Keep Your Home. See What’s Possible

Buy Your Next Home

Specialist Let to Buy Lenders

Keep Your Current Home

Let to Buy Mortgages

Faster Mortgage Decisions

Same-Day DIP Available

Helping Homeowners Move Without Selling

Real reviews from landlords who receive expert advice aligned with their accountants’ expectations

Posted on Google Google
Steve Riley profile picture
Steve Riley
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Great service, prompt replies, kept us up to date frequently. Only one issue due to a miscommunication which was resolved, thank you.
Posted on Google Google
Tracy Davies profile picture
Tracy Davies
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Lyndsey has supported us to secure a mortgage offer. Would recommend his services if need professional advice on mortgage applications and options available.
Posted on Google Google
Annabelle Pearson profile picture
Annabelle Pearson
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Lyndsey Rowe of West Wales Money, who has 30 years experience was recommended to us. He has been professional,prompt with up to date progress on our business dealings, always available and easy to communicate with, we couldn’t recommend him highly enough. Thank you.
Posted on Google Google
Jamie Davies profile picture
Jamie Davies
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We couldn’t recommend Lyndsey highly enough! As first-time buyers, the mortgage process felt quite daunting, but Lyndsey made everything so straightforward and stress-free from start to finish. We received excellent service throughout, with great communication, support and guidance every step of the way. We’re so grateful for all the help in getting us our mortgage and making our first home purchase possible. We wouldn’t hesitate to recommend Lyndsey to anyone looking for a mortgage broker, and we’ll definitely be returning in the future. Thank you so much for all your help!
Posted on Google Google
Richard Godsall profile picture
Richard Godsall
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I was very lucky to have had Lyndsey Rowe(West Wales money) recommended to me by a business colleague and have had an impeccable service from him . He has been extremely helpful and I can not rate him high enough - he has had 36 years experience in this field & it shows!!
Posted on Google Google
Samantha Davies profile picture
Samantha Davies
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We honestly couldn’t recommend Lyndsey highly enough. From the very beginning, he has been incredibly professional, knowledgeable and supportive throughout what can be a very stressful process. As first-time buyers, we had lots of questions and uncertainties, but Lyndsey took the time to explain everything clearly and kept us informed every step of the way. Nothing ever felt like too much trouble, and he was always quick to respond to emails and calls, giving us complete confidence that we were in safe hands.
Posted on Google Google
Sam Bannon profile picture
Sam Bannon
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
We have had an excellent experience with Lyndsey Rowe at West Wales Money. From the very beginning, Lyndsey has been clear, professional, responsive and extremely reassuring throughout what can otherwise be quite a stressful process. His advice has been invaluable, and he has made everything feel straightforward and seamless from our side. He has guided us carefully through the mortgage application process, kept us informed at each stage, and helped us secure our mortgage offer with confidence. We are very grateful for all of Lyndsey’s help so far and would be very happy to recommend him to anyone looking for knowledgeable, trustworthy and supportive mortgage advice.
Posted on Google Google
Liam Dix profile picture
Liam Dix
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I cannot recommend Lyndsey and his team at West Wales Money enough. Myself and my partner are both first time buyers and we did not understand the process fully. He made the process clear with constant communication and updated us regular through every step of the process. We will definitely be using him again when we are due for our renewal.
Posted on Google Google
Sally Edwards profile picture
Sally Edwards
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Lyndsey and his team are fantastic. They’ve made the whole process of buying a house so much easier. Communication is always quick, professional and friendly. My partner and I have felt supported throughout the whole process. We can’t recommend Lyndsey and his team enough, we’re so grateful to them!
Posted on Google Google
billkelly888 profile picture
billkelly888
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Outstanding service from Lyndsey from start to finish. Very patient with all our questions and kept us informed of progress promptly. Would highly recommend Lyndsey and will most certainly use him again!

WHAT IS A LET TO BUY MORTGAGE?

A Let to Buy mortgage allows you to move home without selling your current property.

Instead, you:

🏠 Convert your existing home to Buy to Let
💰 Release equity for your deposit
📄 Secure a residential mortgage for your onward purchase
📈 Retain your original property as a long-term investment

It sounds simple.

In reality, it involves two separate mortgage approvals under different lending criteria.

🏡 The Buy-to-Let lender assesses rental income, ICR stress testing and loan-to-value.

📊 The residential lender assesses affordability, income structure and existing liabilities.

Both mortgages must pass independently.

🔗 And they must align.

If one fails, the entire plan can collapse.

That’s why Let to Buy must be structured correctly from the outset.

WHY MANY LET TO BUY PLANS FALL APART

Let to Buy is one of the most mis-structured mortgage strategies in the UK.

The mistake? Treating two mortgages as separate applications instead of one coordinated plan.

Without proper strategy, applications fail for predictable reasons:

⚠️ Rental income failing ICR stress testing
⚠️ Overestimated rental projections
⚠️ Insufficient equity after valuation
⚠️ Residential affordability reduced by the Buy-to-Let commitment
⚠️ Dividend or bonus income assessed conservatively
⚠️ Lenders selected independently rather than as a compatible pair

If one lender declines, the onward purchase can be placed at risk.
WHY ICR STRESS TESTING CAUSES LET TO BUY DECLINES

Worried your rental income won’t pass stress testing?

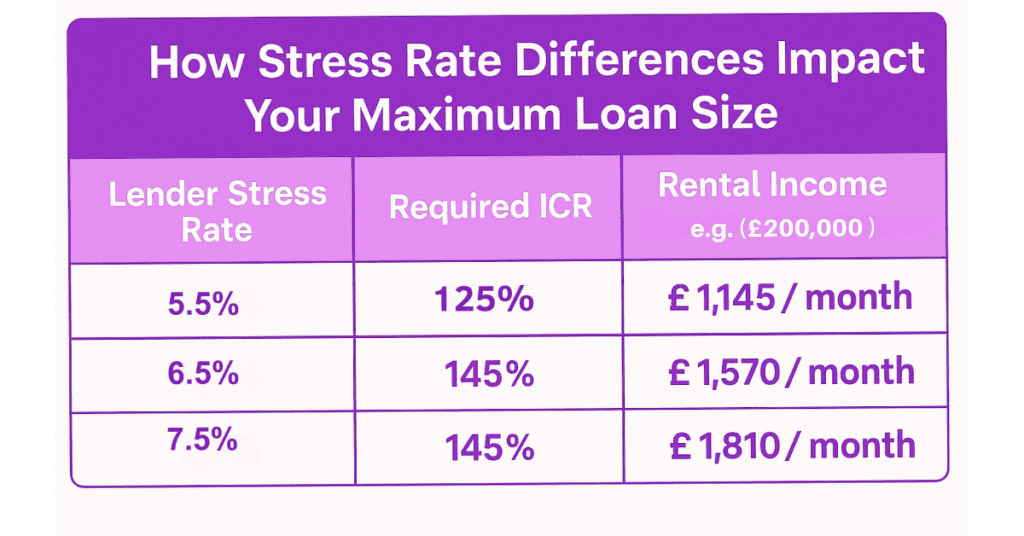
Many Let to Buy applications fail because rental income is assessed using stressed interest rates — not the headline deal rate you secure.

That means:

⚠️ Stress rates can be set as high as 7.5%, even if you’re fixing at a much lower rate
⚠️ ICR thresholds typically range from 125–145%, rising to around 160% for higher-rate taxpayers
⚠️ You may be required to reduce borrowing or inject a larger deposit
⚠️ The equity you expected to release can shrink — directly impacting your onward purchase

Higher-rate taxpayers are often assessed more conservatively, which can materially reduce the deposit available for your residential move.

If the rental side fails stress testing, your residential mortgage may no longer stack up.

And the entire move is placed at risk.

HOW LENDERS ASSESS LET TO BUY MORTGAGES

Buy-to-Let Mortgage Assessment

🏠 Rental income must meet ICR stress tests (typically 125–145%, rising to around 160% for higher-rate taxpayers)
🏠 Loan-to-value usually capped at 75–80%
🏠 Valuation and rental demand assessed
🏠 Background income may influence stress rates

Residential Mortgage Assessment

🏡 Full affordability assessment
🏡 Income multiples vary by lender
🏡 Existing mortgage commitments included
🏡 Dividend, bonus or complex income must be structured correctly

Both applications must pass independently.

But they must also align strategically.

UK Let to Buy Mortgage Specialist – Structuring Both Sides Together

Specialist Buy-to-Let Mortgage Broker

📞 Want to Talk This Through?

Ready to discuss your mortgage needs? Call Lyndsey directly

Call: 07508 147884

Hi, I'm Lyndsey!

Let to Buy requires careful coordination between two lenders, two underwriting frameworks and two affordability models.

The margin for error is small.
If one side is miscalculated, the entire onward purchase can be placed at risk.
I structure both mortgages together from the outset — modelling rental income and residential affordability side by side so they align correctly.

You’ll deal directly with me throughout.

I focus on:

✅ Accurate rental and ICR modelling
✅ Conservative equity calculations
✅ Strategic lender pairing
✅ Coordinated application timing

So your move is controlled, structured and positioned correctly from day one.

My mission?

To help homeowners move forward without being forced to sell a valuable property asset — while protecting their onward purchase.

REAL LIMITED COMPANY BUY-TO-LET RESULTS

NEW TO LET TO BUY? AVOID COMMON STRUCTURING MISTAKES

Designed for homeowners planning to keep their current property and move forward safely

WHAT HAPPENS WHEN YOU BOOK A DISCOVERY CALL

Focused mortgage broker working on a laptop, providing personalised buy-to-let mortgage solutions.

Dual Mortgage Advice in 4 Structured Steps 

📞 Step 1: Review Your Equity & Plans
I will assess your current property value, outstanding mortgage, rental potential and onward purchase plans.

📦 Step 2: Dual Mortgage Modelling
I model Buy-to-Let stress testing and residential affordability side by side — including ICR, deposit release and income structure.

📦 Step 3: Strategic Lender Pairing
I select compatible lenders whose criteria align — so both mortgages work together, not against each other.

📦 Step 4: Coordinated Submission & Management
Both applications are sequenced and managed carefully to protect your onward purchase and minimise decline risk

Trusted Partners for Your Mortgage Needs

Discover Better Deals and Reduce Your Monthly Repayments Through Specialist Lenders

CASE STUDY 1 – SARAH & JAMES, BRISTOL & SWANSEA

The Situation
Sarah and James lived separately and wanted to buy a home together while retaining both of their existing properties as rental investments.

This meant three mortgages needed to work together without jeopardising their onward purchase.

Key Risks
⚠️ Two properties needing to pass ICR stress testing
⚠️ Equity release aligned with deposit requirements
⚠️ Residential affordability assessed across combined incomes
⚠️ Coordinating three approvals without breaking the chain

The Strategy
🔍 Modelled rental income at stressed rates across multiple lenders
📊 Structured equity release conservatively to protect deposit strength
🔗 Paired compatible lenders for all three mortgages
📅 Sequenced applications to minimise timing risk

Outcome
✅ Both properties successfully converted to Buy to Let
✅ Rental income passed stress testing comfortably
✅ Residential mortgage approved
✅ Purchase completed without disruption
✅ Long-term assets retained

Client Testimonial
“Three mortgages needed to work together. Lyndsey structured everything properly from the outset. We kept both properties and completed without disruption.”

CASE STUDY 2 – DAVID, CARDIFF

The Situation

David, a company director in Cardiff, wanted to move to a larger family home while retaining his existing property as a rental.

On the advice of his accountant, he wanted the Buy-to-Let purchase structured through a limited company for long-term tax efficiency.

Key Risks

⚠️ Rental income passing ICR stress testing
⚠️ Dividend income affordability on the residential side
⚠️ Aligning limited company borrowing with personal affordability
⚠️ Managing both approvals without risking the onward purchase

The Strategy

🔎 Modelled rental income across multiple lenders at stressed rates
📊 Structured salary and dividend income to maximise residential affordability
🏢 Arranged the Buy-to-Let purchase through an accountant-approved limited company structure
🔗 Paired lenders whose criteria aligned strategically
📅 Sequenced both applications to protect the onward chain

The Outcome

✅ Converted existing home to Buy-to-Let at 75% LTV
✅ Rental income passed 145% ICR comfortably
✅ Residential mortgage approved using dividend income
✅ Completed purchase without disrupting the chain

Client Testimonial

“I wanted to move up without selling, but also structure it properly for the future. Lyndsey aligned everything from day one. Both mortgages were approved smoothly and the limited company setup was handled correctly.”

MOVE HOME WITHOUT SELLING — STRUCTURE BOTH MORTGAGES CORRECTLY FROM DAY ONE

🏠 Let-to-Buy Specialist

Get one-to-one Let to Buy advice structured around your goals — with clear, straightforward guidance and no pressure.

Book Your Let to Buy Discovery Call

UK-WIDE LET TO BUY SPECIALIST | DUAL MORTGAGE STRUCTURING | 170+ LENDERS

30+ years’ experience No obligation Speak directly to a specialist

Eligibility for a mortgage is subject to status, credit checks, and affordability assessments in accordance with FCA regulations.

West Wales Money Ltd is registered with the Data Protection Act 2018 registration No ZA579253 and is authorised and regulated by the Financial Conduct Authority under Firm Reference No: 1005183 as an Appointed Representative of TMG Direct Limited which is authorised and regulated by the Financial Conduct Authority under Firm Reference No: 786245 and registered with the Data Protection Act 1998 registration No: ZA178200.

YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.

Think carefully before securing debts against your home. Your home may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it. The guidance and/or advice contained within this website is subject to the UK regulatory regime and is therefore targeted at consumers based in the UK.

Fill in your details below to get a call back for your free mortgage review.