Mortgage Broker Carmarthen & West Wales

SPV MORTGAGES FOR

PROPERTY INVESTORS


Specialist SPV and Limited Company Buy-to-Let mortgage advice for property investors

Same-Day DIP Available

Access 170+ Lenders

Speak Directly to a Specialist

Request a Call Back

Finance Your SPV

Specialist SPV Lenders

Grow Your Portfolio

SPV Mortgage Specialists

Speak to a Specialist

Dedicated SPV Advice

Trusted by SPV landlords and property investors

Why Are SPV Landlords Being Restricted — Even on Strong Deals?

Could This Be Holding You Back?

If you’ve been declined or offered less than expected, your lender’s criteria could be limiting your borrowing.

Rental income doesn't meet the lender's stress test

Maximum borrowing lower than expected

Portfolio exposure restricting your options

SPV structure doesn't meet lender criteria

Property type outside standard criteria

Deposit or source of funds not accepted

You Could Have More Options

One lender saying no doesn't necessarily mean the deal doesn't work. Different lenders assess SPV mortgages in different ways.

Different lenders use different rental stress tests

Portfolio criteria vary between lenders

Some lenders accept more complex property types

Specialist lenders may offer more flexible criteria

How Lenders Reduce Your Borrowing — Without You Realising

Why Your Borrowing Is Being Reduced

Lenders don't all assess rental income in the same way. Different stress rates and rental cover requirements can produce very different borrowing limits.

  • Rental income may be assessed more conservatively than you expect
  • Higher stress rates can reduce your borrowing capacity
  • You may be asked to reduce the loan or increase your deposit
  • Different lenders can produce very different borrowing outcomes

👉 Choosing the right lender could make a significant difference to how much you can borrow.

How Stress Testing Can Reduce Your Borrowing

Illustrative example:
Same property. Same rental income. Same assumed stress rate.

Rental
Cover
Illustrative
Max Borrowing
Reduction
125%
£308,246 Illustrative borrowing
Highest
145%
£265,729 Illustrative borrowing
− £42,517
160%
£240,817 Illustrative borrowing
− £67,429

Illustrative example only. Actual borrowing will depend on the lender's rental calculation, stress rate, product, property and individual circumstances.

How I Help SPV Landlords Find the Right Mortgage

The Right SPV Lender Could Make All the Difference

STEP 1: Understand Your Property & Portfolio

I review the property, rental income, LTV and borrowing required

STEP 2: Match Your SPV to the Right Lenders

I compare lender criteria and rental stress testing

STEP 3: Present Your Application Properly

Your case is presented correctly from the outset

30+ years’ experience navigating complex mortgage criteria.

SPV Mortgage Solutions for Property Investors

Whether you're buying your next investment, refinancing an existing property or growing your portfolio, I can help you explore suitable SPV mortgage options.

🏠

SPV Property Purchase

Finance your next Buy-to-Let property through a limited company.

SPV Remortgage

Review your existing mortgage and explore alternative lender options.

📈

Portfolio Landlords

Mortgage solutions for landlords with multiple investment properties.

£

Capital Raising

Release equity from existing property for investment or other eligible purposes.

🏢

HMO & Multi-Unit Properties

Specialist mortgage options for more complex investment properties.

Growing Your Portfolio

Explore borrowing options to support your next property investment.

REAL SPV MORTGAGE SUCCESS STORIES:
SEE WHAT’S POSSIBLE

BORROWED £415,000 After being restricted elsewhere

Initially capped at £327,000 due to stress testing and lender criteria. After reviewing the case and identifying a more suitable specialist SPV lender, the borrowing increased significantly.

  • Increased borrowing by £88,000
  • More suitable lender identified
  • Application successfully progressed

REMORTGAGED 12 PROPERTIES To fund the purchase of 5 more

A portfolio landlord remortgaged 12 existing properties within their SPV, raising £1,450,000 in capital to help fund the purchase of a further five investment properties.

  • £1,450,000 capital raised
  • 12 properties successfully remortgaged
  • 5 additional properties purchased
  • Portfolio expanded from 12 to 17 properties

Why SPV Landlords Choose West Wales Money

Borrow more with expert, one-to-one advice — not a call centre

30+ years’ experience — helping clients navigate complex mortgage criteria

Access to 170+ lenders — including specialist Buy-to-Let and SPV options

SPV mortgage expertise — understanding rental stress tests, LTV and lender

Portfolio landlord experience — from single properties to growing portfolios

One-to-one advice — deal directly with me from enquiry through to completion

The result? A mortgage strategy matched to your SPV, property and investment plans.

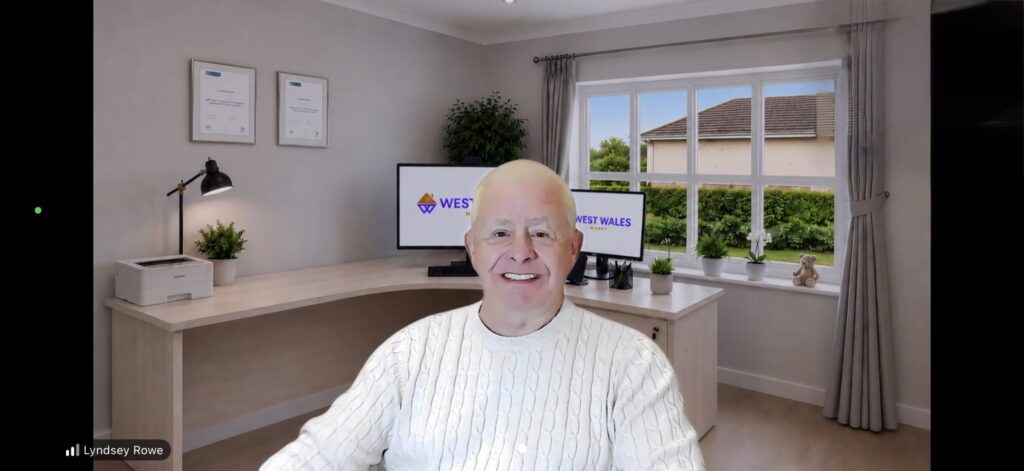
Lyndsey Rowe, Mortgage & Protection Adviser at West Wales Money, in his home office during a video consultation with dual monitors displaying the West Wales Money logo.

Lyndsey Rowe

Mortgage & Protection Adviser

CeMAP & CeRER Qualified
30+ Years’ Experience

— FREQUENTLY ASKED QUESTIONS —

DO YOU CHARGE FEES?

Yes — I charge a professional fee for specialist mortgage advice and service

CAN I GET A MORTGAGE THROUGH AN SPV?

Yes — many Buy-to-Let lenders accept SPV limited companies. I’ll help find suitable options

DO I NEED TO SET UP MY SPV FIRST?

Not always. I’ll help ensure your SPV structure meets lender requirements before applying

HOW MUCH CAN I BORROW WITH AN SPV MORTGAGE?

This depends on the property value, rental income, deposit and rental stress tests

CAN FIRST-TIME LANDLORDS GET AN SPV MORTGAGE?

Yes — some lenders accept first-time landlords using an SPV, subject to their criteria

How It Works
1

Discovery Call

We discuss your property and
investment plans.

2

SPV & Rental Review

We review your SPV, property, deposit
and expected rent.

3

Lender Research

I search for lenders
that match your
circumstances.

4

Mortgage Options

You receive a clear
recommendation.

5

Application Support

I manage your application through
to completion.

The SPV Buy-to-Let Mortgage Guide

Created with accountant input to help landlords set up SPVs correctly from day one

30+ years’ experience No obligation Speak directly to a specialist

Eligibility for a mortgage is subject to status, credit checks, and affordability assessments in accordance with FCA regulations.

West Wales Money Ltd is registered with the Data Protection Act 2018 registration No: ZA579253 and is authorised and regulated by the Financial Conduct Authority under Firm Reference No: 100​5183 as an Appointed Representative of TMG Direct Limited which is authorised and regulated by the Financial Conduct Authority under Firm Reference No: 786​245 and registered with the Data Protection Act 1998 registration No: ZA178200.

YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.

Think carefully before securing debts against your home. Your home may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it. The guidance and/or advice contained within this website is subject to the UK regulatory regime and is therefore targeted at consumers based in the UK.

Fill in your details below to get a call back for your free mortgage review.