Business borrowing can play an important role in helping a company grow, invest in property, purchase equipment, manage cash flow or fund expansion.
But what would happen to those financial commitments if a director, business owner or other key person died or became seriously ill?
The business may still be responsible for repaying its loans, commercial mortgage or other borrowing at a time when its income and financial stability are already under pressure.
Business Loan Protection can provide a financial safety net by helping the company repay outstanding borrowing following the death or, where included, diagnosis of a specified critical illness of an insured person.
This guide explains how Business Loan Protection works, what types of borrowing may be protected and how to consider the appropriate level of cover for your company.
 What Happens to Business Loans If a Director Dies?
 What Happens to Business Loans If a Director Dies?
Business borrowing does not normally disappear simply because a director, shareholder or key person dies.
The company may still have commitments such as:
❌ Business loans
❌ Commercial mortgages
❌ Director’s loan accounts
❌ Asset finance
❌ Overdrafts
❌ Other forms of business borrowing
At the same time, the loss of an important individual could affect revenue, customer relationships, management and the company’s ability to meet its financial commitments.
Where borrowing has been supported by a personal guarantee, the position may also need careful consideration.
Business Loan Protection is designed to provide funds that can help the company deal with some or all of its outstanding borrowing following a valid claim.
Could Your Business Repay Its Borrowing Without You?
Consider what would happen if one of the people responsible for generating income, managing the company or securing important customer relationships was suddenly no longer there.
Would the business still be able to make its loan repayments?
Would cash reserves need to be used?
Could the company continue servicing a commercial mortgage?
Would lenders review existing borrowing arrangements?
Could other directors or shareholders need to inject additional capital?
For many businesses, the problem isn’t simply the amount owed. It is having to deal with that debt at the same time as the company is adjusting to the loss of an important person.
Business Loan Protection can help provide financial breathing space at precisely that point.
What Is Business Loan Protection?
 What Is Business Loan Protection?
Business Loan Protection is a form of protection designed to help a company repay outstanding business borrowing if an insured director, owner or other key individual dies during the term of the protection plan.
Critical Illness Cover may also be available, depending on the protection plan selected.
Following a successful claim, a lump sum is normally paid to the business.
The money can then help the company repay or reduce relevant borrowing, helping protect its balance sheet and financial stability.
Business Loan Protection can potentially be used in connection with borrowing such as:
✓ Commercial mortgages
✓ Business loans
✓ Director’s loans
✓ Overdraft facilities
✓ Certain asset finance arrangements
✓ Other qualifying business debts
The appropriate arrangement will depend on the type of borrowing, who is responsible for it and the structure of the business.
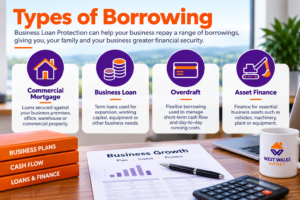
What Types of Business Borrowing Can Be Protected?
Businesses can borrow money in many different ways, so Business Loan Protection isn’t necessarily limited to a conventional bank loan.
Depending on the circumstances, protection may be considered for:
✓ Commercial mortgages
✓ Bank loans
✓ Business expansion loans
✓ Director’s loan accounts
✓ Overdrafts
✓ Asset or equipment finance
✓ Other business borrowing
For example, a company may have borrowed £300,000 to purchase its premises and another £75,000 to invest in equipment.
If the director primarily responsible for generating the company’s income died, the business could potentially face £375,000 of borrowing while simultaneously experiencing a reduction in revenue.
The first step is therefore identifying exactly what the business owes and what financial risk would arise if a key individual were lost.
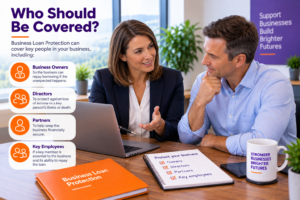
Who Should Be Covered?
Business Loan Protection isn’t necessarily required for every director or employee.
The people considered for protection will usually be those whose death or serious illness could materially affect the company’s ability to repay its borrowing.
This could include:
✓ Managing directors
✓ Business owners
✓ Company founders
✓ Shareholders
✓ Directors responsible for generating significant revenue
✓ Individuals whose personal guarantee supports borrowing
✓ Other key people on whom the company’s financial stability depends
Different people may represent different levels of financial risk to the business.
That is why Business Loan Protection should be considered alongside the company’s borrowing structure rather than simply arranging identical amounts of cover for every director.
How Much Business Loan Protection Do You Need?
 How Much Business Loan Protection Do You Need?
There isn’t a single amount of Business Loan Protection that’s suitable for every company.
A useful starting point is to establish the company’s outstanding borrowing.
This could include:
✓ Outstanding business loans
✓ Commercial mortgage balances
✓ Director’s loan accounts
✓ Overdraft facilities
✓ Relevant asset finance
✓ Other business debts
You should also consider whether the borrowing is reducing over time and how long it is expected to remain outstanding.
For example, if your company has a £250,000 commercial mortgage and a £50,000 business loan, there could potentially be £300,000 of borrowing to consider.
The appropriate amount and term of protection will depend on the individual circumstances of the business and its borrowing.
Can Business Loan Protection Include Critical Illness Cover?
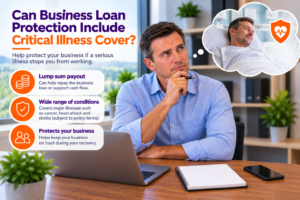 Can Business Loan Protection Include Critical Illness Cover?
Yes. Business Loan Protection may be arranged with Critical Illness Cover, subject to the insurer’s terms, underwriting and the protection plan selected.
This can be particularly relevant because the financial impact on a business doesn’t only arise following someone’s death.
A director suffering a serious illness could be absent from the business for a considerable period while the company continues to make its loan repayments.
Where Critical Illness Cover is included, the protection plan may provide a lump sum following diagnosis of one of the specified conditions covered by the insurer, subject to its definitions and terms.
The money could then help reduce or repay relevant business borrowing.
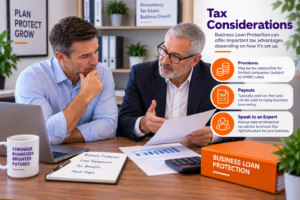
Business Loan Protection: Tax Considerations
Tax treatment is an important consideration when arranging Business Loan Protection.
The tax position can depend on factors including:
- Who owns the protection plan
- Who is insured
- The purpose of the cover
- The relationship between the insured person and the borrowing
- How any proceeds would be used
The tax treatment of premiums and any potential claim proceeds can vary depending on the circumstances.
For this reason, Business Loan Protection should not be arranged based solely on assumptions about tax treatment.
I can help structure the protection appropriately from an insurance perspective, while your accountant or tax adviser can provide guidance on the tax treatment for your particular business.
Business Loan Protection in Practice
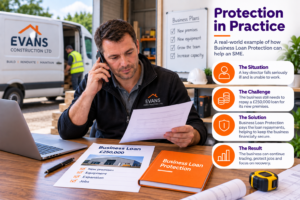 Business Loan Protection in Practice
Consider a limited company with:
❌ £250,000 commercial mortgage
❌ £75,000 business loan
❌ £25,000 overdraft facility
The company therefore has significant financial commitments.
One of its directors is responsible for a substantial proportion of its revenue and has played an important role in obtaining the company’s borrowing.
If that director died unexpectedly, the business could experience a reduction in income while still having to service its existing debts.
Appropriate Business Loan Protection could provide a lump sum following a successful claim, giving the company funds to reduce or repay some or all of the relevant borrowing.
That could reduce financial pressure on the remaining directors and give the company greater flexibility at a difficult time.
Business Loan Protection vs Key Person Protection
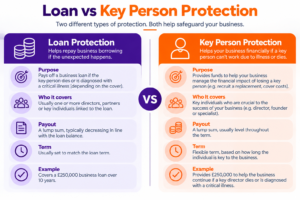 Business Loan Protection vs Key Person Protection
These two types of Business Protection are related, but they address different financial risks.
Business Loan Protection
Designed primarily to help a company repay or reduce outstanding business borrowing following the death or, where covered, serious illness of an insured individual.
The amount of cover is generally linked to the relevant business debt.
Key Person Protection
Designed to help protect the business against the wider financial impact of losing an important person.
This could include:
✓ Lost profits
✓ Recruitment costs
✓ Reduced sales
✓ Disruption to customer relationships
✓ Cost of replacing specialist knowledge or expertise
A company may therefore need both types of protection.
One helps address its borrowing; the other helps protect the wider financial performance of the business.
What About Personal Guarantees?
 What About Personal Guarantees?
This deserves its own section because it is particularly relevant to company directors.
Some lenders may require directors or business owners to provide personal guarantees when arranging business borrowing.
A personal guarantee can potentially expose the guarantor to personal liability if the company cannot meet its obligations, depending on the terms of the guarantee.
The death of a director does not automatically mean every personal guarantee will be dealt with in the same way.
The terms of the borrowing and guarantee need to be checked carefully.
Business Loan Protection may form part of the company’s wider strategy for managing this risk by providing funds that can help repay or reduce the underlying business debt.
Where a personal guarantee is involved, appropriate legal advice should also be considered.
Why Specialist Business Protection Advice Matters
 Why Specialist Business Protection Advice Matters
Business Loan Protection isn’t simply about matching a life insurance amount to the balance of a loan.
You first need to understand the company’s borrowing, who is responsible for it and what would happen financially if an important director or business owner died or became seriously ill.
As part of my advice process, I can help you consider:
✓ The company’s existing borrowing
✓ Which individuals should be insured
✓ An appropriate level of protection
✓ Life and Critical Illness Cover options
✓ The appropriate term
✓ Existing Business Protection already in place
✓ Affordability and suitable providers
✓ How Business Loan Protection fits alongside Key Person and Shareholder Protection
✓ Areas to discuss with your accountant, tax adviser or solicitor
I work directly with company directors on a one-to-one basis, helping identify the financial risks within their business and arrange appropriate protection.
Frequently Asked Questions About Business Loan Protection
 Frequently Asked Questions About Business Loan Protection
What is Business Loan Protection?
Business Loan Protection is designed to provide a lump sum following a successful claim that can help a company repay or reduce relevant business borrowing if an insured person dies or, where included, suffers a specified critical illness.
Who owns Business Loan Protection?
The appropriate ownership structure depends on the business and borrowing arrangement. This should be established when the protection is arranged.
What types of loans can be protected?
Depending on the circumstances, this may include business loans, commercial mortgages, director’s loans, overdrafts and certain other forms of business borrowing.
Does Business Loan Protection cover personal guarantees?
Business Loan Protection protects against the underlying financial risk rather than changing the legal terms of a personal guarantee. The borrowing and guarantee documentation should be reviewed carefully and legal advice may be required.
Can Critical Illness Cover be included?
Potentially, yes. Critical Illness Cover may be available subject to the insurer, underwriting and protection plan selected.
How much Business Loan Protection do I need?
This will depend on the amount and type of borrowing, how the debt reduces over time, the individuals connected with the borrowing and the financial circumstances of the company.
Is Business Loan Protection the same as Key Person Protection?
No. Business Loan Protection primarily addresses business debt, whereas Key Person Protection is designed to address the wider financial impact of losing an important person.
A business may require both.
 Does Your Business Have Borrowing That Needs Protecting?