Your business may rely heavily on a small number of people. This could be a director, founder, salesperson, technical specialist or another employee whose knowledge, relationships or experience are particularly important to the company’s success.
But what would happen financially if one of those people died or became seriously ill?
The loss of a key person could affect revenue, profitability, customer relationships and the day-to-day running of the business. You may also face recruitment costs or need additional funding while the company adjusts.
Key Person Protection Insurance can provide a financial safety net, helping the business manage the financial impact of losing someone critical to its success.
 What Happens to Your Business If a Key Person Dies?
 What Happens to Your Business If a Key Person Dies?
The death or serious illness of an important person can have consequences far beyond simply needing to recruit a replacement.
Depending on their role, the business could experience:
❌ Loss of revenue or profits
❌ Disruption to important customer relationships
❌ Delays to projects or contracts
❌ Recruitment and training costs
❌ Loss of specialist knowledge or experience
❌ Pressure on existing directors and employees
❌ Difficulty meeting existing financial commitments
For some businesses, particularly smaller companies where knowledge and responsibilities are concentrated among only a few people, the financial impact could be significant.
What Happens If Your Business Can’t Easily Replace Them?
Finding someone with the same skills, knowledge and relationships can take time.
Imagine a business generates £1 million in annual turnover, but one director is responsible for a significant proportion of its new business and key customer relationships.
If that director unexpectedly dies or becomes seriously ill, replacing their contribution may take months.
During that period, the company could experience falling revenue at exactly the same time as it faces recruitment, training and potentially additional staffing costs.
Without sufficient cash reserves, that can put considerable pressure on the business.
Key Person Protection can provide a lump sum to help the company manage that financial disruption.
What Is Key Person Protection Insurance?
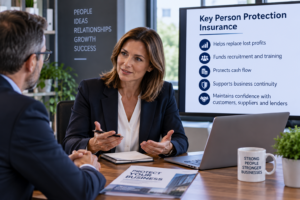 What Is Key Person Protection Insurance?
Key Person Protection Insurance is a protection plan taken out by a business on the life of an individual whose death or serious illness could have a significant financial impact on the company.
The business normally pays the premiums and receives the proceeds of a successful claim, subject to how the arrangement has been established.
The funds could help the company:
✔ Replace lost profits
✔ Recruit and train a replacement
✔ Protect cash flow
✔ Meet ongoing business expenses
✔ Maintain confidence among customers, suppliers and lenders
✔ Give the company time to reorganise following the loss of a key individual
The purpose isn’t to replace the person themselves. It is to help protect the business against the financial consequences of losing them.
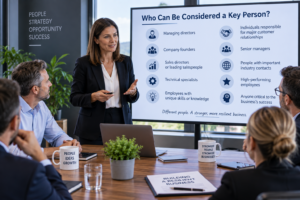
Who Can Be Considered a Key Person?
A key person doesn’t necessarily have to be the managing director or owner of the company.
It could be anyone whose contribution is particularly important to the financial success of the business.
Examples could include:
✔ Managing directors
✔ Company founders
✔ Sales directors or leading salespeople
✔ Technical specialists
✔ Employees with unique skills or knowledge
✔ Individuals responsible for major customer relationships
✔ Senior managers
✔ People with important industry contacts
A useful question for a company director to consider is:
“Would the business suffer financially if this person wasn’t here tomorrow?”
If the answer is yes, it may be worth considering whether Key Person Protection is appropriate.
Key Person Protection: Tax Considerations
The tax treatment of Key Person Protection depends on how the protection is structured, the purpose of the arrangement and the relationship between the company and the person being insured.
In certain circumstances, premiums may potentially be treated as an allowable business expense, but this should never be assumed.
The tax treatment of any proceeds can also depend on the circumstances.
Tax legislation and HMRC practice can change, so the company’s accountant or tax adviser should confirm the tax treatment applicable to the business.
How Much Key Person Protection Do You Need?
 How Much Key Person Protection Do You Need?
There isn’t a single amount that’s appropriate for every business.
The level of protection should reflect the potential financial loss the company could experience if the key person died or became seriously ill.
Factors that may need to be considered include:
✔ The person’s contribution to company profits
✔ Revenue directly attributable to them
✔ Recruitment and replacement costs
✔ The time required to recruit and train a replacement
✔ Loss of important customers or contracts
✔ Existing cash reserves
✔ Outstanding business debts
✔ The length of time the business may need financial support
For example, if a key salesperson generates a substantial proportion of a company’s annual revenue, simply covering their salary is unlikely to reflect their true financial value to the business.
This is why establishing an appropriate level of cover requires more than looking at someone’s earnings.
Can Key Person Protection Include Critical Illness Cover?
 Can Key Person Protection Include Critical Illness Cover?
Yes. Key Person Protection can potentially include Critical Illness Cover as well as life cover.
This can be particularly important because a business could experience significant financial disruption even though the key person survives.
A serious illness could prevent a director or employee from working for an extended period, potentially affecting revenue, customers and the management of the company.
If the insured person is diagnosed with a specified critical illness covered by the protection plan, a successful claim could provide funds to help the business manage during this period.
The illnesses covered and definitions used vary between providers, so these should be considered carefully when selecting a protection plan.
Key Person Protection in Practice
 Key Person Protection in Practice
Consider a successful engineering company employing 20 people.
One of its directors has specialist technical knowledge and manages several of the company’s largest customer relationships.
The company estimates that replacing the director could take between six and twelve months.
If the director unexpectedly dies, the business could face:
❌ Reduced revenue
❌ Potential loss of customers
❌ Recruitment costs
❌ Temporary consultancy costs
❌ Additional pressure on the remaining directors
An appropriately arranged Key Person Protection plan could provide the company with a lump sum.
This doesn’t replace the director’s knowledge or relationships, but it provides valuable financial breathing space while the company recruits, reorganises and protects its future.
Key Person Protection vs Shareholder Protection
 Key Person Protection vs Shareholder Protection
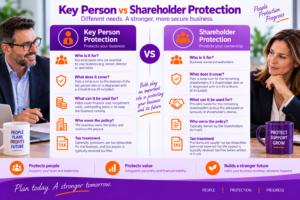
These two forms of Business Protection are sometimes confused, but they serve different purposes.
Key Person Protection
Protects the business financially.
The protection is designed to help compensate the company for the financial impact of losing an important individual through death or, where included, a specified critical illness.
Shareholder Protection
Protects the ownership of the business.
It can provide funds to help the remaining shareholders purchase the shares of a shareholder who dies or becomes critically ill, depending on the arrangement.
A company may therefore need both types of protection.
One helps protect the financial performance of the business; the other helps protect its ownership and control.
Why Specialist Protection Advice Matters
Key Person Protection isn’t simply about choosing an insurer and selecting an amount of cover.
The first step is understanding who your business genuinely depends on and what the financial consequences could be if that person died or became seriously ill.
As part of my advice process, I can help you consider:
✓ Which individuals are key to the success of your business
✓ The potential financial impact of losing them
✓ An appropriate level of protection
✓ Life and Critical Illness Cover options
✓ How long the protection should be in place
✓ Any existing Business Protection you already have
✓ Affordability and suitable providers
✓ Areas that should be discussed with your accountant or tax adviser
I work directly with company directors on a one-to-one basis, helping you understand the risks your business faces and arrange appropriate protection to help safeguard its financial future.
Frequently Asked Questions About Key Person Protection
 Frequently Asked Questions About Key Person Protection
What is Key Person Protection Insurance?
Key Person Protection is designed to provide financial support to a business following the death or, where included, diagnosis of a specified critical illness of an important director or employee.
Who can be insured as a key person?
A key person could be a director, founder, salesperson, technical specialist or another employee whose loss could have a significant financial impact on the business.
Who receives the money from a Key Person Insurance claim?
With a typical company-owned Key Person Protection arrangement, the business owns the protection plan and would receive the proceeds of a successful claim. The exact structure should be established correctly when the cover is arranged.
Is Key Person Insurance tax deductible?
The tax treatment depends on the purpose and structure of the protection. Premiums may potentially qualify as a business expense in certain circumstances, but this should not be assumed. Your accountant or tax adviser should confirm the position.
Can Key Person Protection include Critical Illness Cover?
Yes. Depending on the provider and protection selected, Critical Illness Cover can potentially be included alongside life cover.
How much Key Person Insurance does my business need?
The appropriate amount depends on the financial impact the loss of that individual could have on the company. Their contribution to profits, revenue, replacement costs, customer relationships and the time required for the business to recover may all need to be considered.
What’s the difference between Key Person Insurance and Shareholder Protection?
Key Person Insurance primarily protects the business against financial loss. Shareholder Protection is designed to help deal with business ownership and the purchase of shares following the death or serious illness of a shareholder.
 How Much Key Person Protection Does Your Business Need?