If you’re a company director, you may already have life insurance in place or be considering arranging cover to protect your family.
But how you pay for that cover can make a significant difference.
Many directors pay life insurance premiums personally from income they have already taken from their limited company and paid tax on.
Relevant Life Cover offers another option.
It allows your limited company to arrange and pay for life insurance for you as an employee or director. Subject to the relevant rules and your individual circumstances, this can potentially be a more tax-efficient way of protecting your family.
What Happens to Your Family If You Die?
As a company director, your family may depend heavily on the income you generate.
If you were to die unexpectedly, they could still have significant financial commitments, including:
🏠 Mortgage repayments
💷 Household bills
👨👩👧👦 Children and family expenses
🎓 School or university costs
🚗 Loans and other commitments
📈 Future financial plans
Life insurance can provide a lump sum to help your family maintain their financial security at an extremely difficult time.
But there is another question directors should consider:
What is the most appropriate way to pay for that protection?
Why Paying for Life Insurance Personally Can Cost More
Many company directors arrange personal life insurance and pay the monthly premium from their own bank account.
The problem is that the money used to pay that premium has normally already been extracted from the limited company.
Depending on how you take your income, this could mean paying:
❌ Corporation tax within the company
❌ Income tax or dividend tax when money is extracted
❌ National Insurance where applicable
Only then is the remaining personal income available to pay your life insurance premium.
For a company director, there may be another way.
Relevant Life Cover allows the limited company to pay the premium directly.
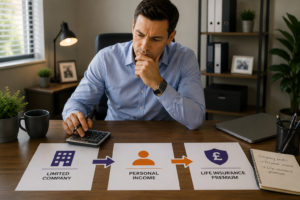
The Financial Cost of Paying Personally
Imagine you want life insurance costing £100 per month.
If you pay the premium personally, your company may need to generate considerably more than £100 of profit for you to end up with £100 of spendable personal income.
This is because tax may be payable before the money reaches your personal bank account.
With Relevant Life Cover, the company pays the premium directly.
Subject to meeting the relevant conditions, premiums may potentially qualify as an allowable business expense for corporation tax purposes.
They are also generally not treated as a benefit in kind for the employee or director.
This can make Relevant Life Cover particularly attractive to directors who currently pay for life insurance personally.
 What Is Relevant Life Cover?
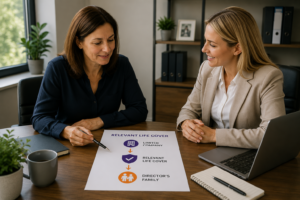 What Is Relevant Life Cover?
Relevant Life Cover is a type of life insurance paid for by an employer for an individual employee.
This can include a director of their own limited company.
The company takes out the protection plan and pays the premiums, while the life assured is the director or employee.
The protection plan is normally written into a Relevant Life trust so that, following a successful claim, the benefit can be paid to the intended beneficiaries.
Relevant Life Cover can provide:
🟢 A lump sum on death
🟢 Financial protection for your family
🟢 Company-paid premiums
🟢 Potential corporation tax advantages
🟢 No personal premium payments from your net income
The exact cover available will depend on the insurer and your circumstances.
Relevant Life Cover: Tax Considerations
One of the main reasons company directors consider Relevant Life Cover is its potential tax efficiency.
Subject to the plan meeting the relevant rules and the company’s circumstances, premiums may potentially qualify as an allowable business expense for corporation tax purposes.
Relevant Life premiums are also generally:
✅ Paid directly by the company
✅ Not treated as a benefit in kind
✅ Not subject to employee National Insurance
✅ Not subject to employer National Insurance
✅ Separate from the employee’s personal pension contributions
The tax treatment of Relevant Life Cover depends on individual circumstances and may change in the future.
You should confirm the tax treatment with your accountant or tax adviser.
There isn’t one solution that is right for every company director.
👤 Personal Life Insurance
You arrange the protection personally.
🟢 Premiums paid from your personal bank account
🟢 Suitable for employed and self-employed individuals
🟢 Can provide life and other protection depending on the plan
🟢 Straightforward personal ownership options
However, the premiums are normally paid from income on which you have already paid tax.
🏢 Relevant Life Cover
Your limited company arranges the protection for you.
🟢 Company pays the premiums
🟢 Potentially tax-efficient
🟢 Usually not treated as a benefit in kind
🟢 Can provide substantial life cover
🟢 Benefit is intended for your chosen beneficiaries via a trust
For eligible company directors, Relevant Life Cover can therefore be worth considering alongside traditional personal life insurance.
A Typical Company Director Scenario
 A Typical Company Director Scenario
Consider a company director with:
🏢 Their own limited company
🏠 A substantial mortgage
👨👩👧 A partner and children
💷 Regular income from the company
🛡️ A need for life insurance
The director currently pays for life insurance personally each month.
Those premiums are being paid from money that has already been extracted from the company and potentially subjected to tax.
Instead, the director explores Relevant Life Cover.
The company pays the premiums directly and the protection is placed into an appropriate trust for the director’s beneficiaries.
This could potentially provide the family protection they need while offering a more tax-efficient way for the company to fund the cover.
Is Relevant Life Cover Right for Your Limited Company?
Relevant Life Cover could be worth considering if you:
✔️ Run your own limited company
✔️ Are a company director
✔️ Want to protect your family financially
✔️ Currently pay for life insurance personally
✔️ Want your company to fund your life cover
✔️ Are looking for a potentially tax-efficient protection solution
✔️ Want additional life cover outside your existing employee benefits
The right solution will depend on your personal circumstances, business structure and protection requirements.
Why Specialist Protection Advice Matters
 Why Specialist Protection Advice Matters
Relevant Life Cover isn’t simply about finding the cheapest life insurance premium.
The protection needs to be structured correctly.
Important considerations include:
📋 How much life cover you need
📅 How long the protection should last
🏢 Your company structure
💷 How premiums will be paid
📜 The Relevant Life trust
👨👩👧👦 Who should benefit from the protection
🛡️ The insurer and protection features
As a Mortgage and Protection Adviser, I can review your circumstances and compare Relevant Life Cover options from a range of insurers.
The aim is to make sure your protection is appropriate for both you and your family.
Protecting Your Family and Your Future
 Protecting Your Family and Your Future